A fire can be put out in a day, yet the financial damage to a business may continue for months. Customers find alternatives, machinery takes time to replace, and rent and wages may still fall due. Business interruption insurance in the UK addresses some of that gap when an insured event disrupts trading. The distinction … Read more
Public Liability Insurance for Small Businesses in the UK
BRUCEORANGE
A customer trips over a cable in your workshop. A decorator damages a client’s flooring. A market trader’s display falls against a visitor’s phone. Such incidents may seem minor at first, but injury and property damage claims can become expensive for a small firm. Public liability insurance for small business owners is designed to help … Read more
Renters Insurance When Moving Home in the UK
BRUCEORANGE
Moving out of a rented property creates a surprisingly awkward insurance question: what happens to your belongings while your address is changing? Your laptop might still be at the old flat, your furniture could be in a removal van, and half your boxes may already be at the new place. Renters insurance when moving home … Read more
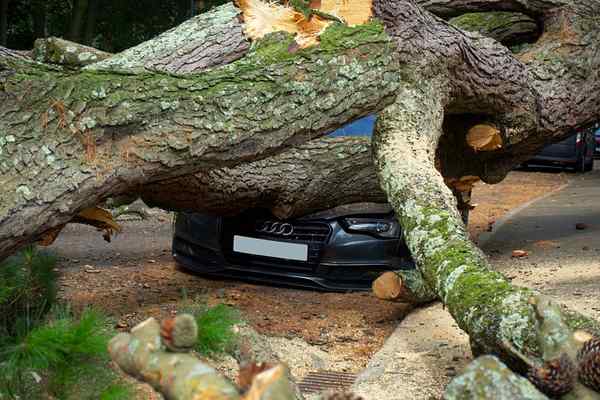
Storm and Escape of Water Damage: What Home Insurance Covers
Storms and burst pipes can both leave a home wet, damaged and uninhabitable, but insurers do not treat every type of water damage in the same way. A roof opened by high winds is usually considered under storm cover, while water from a failed pipe, tank or fixed heating system is normally considered under escape … Read more
What Does Contents Insurance Cover in the UK
Contents insurance protects the belongings you keep in your home rather than the building itself. A useful rule of thumb is to imagine lifting the roof off your home and turning it upside down: many of the things that would fall out are likely to count as contents. That can include furniture, clothing, electricals, kitchenware, … Read more
Agreed Value Cover for Classic Cars: How It Differs From Standard Comprehensive
For a classic-car owner, the awkward question is not simply whether the car is insured. It is what the insurer will pay if the vehicle is stolen or damaged beyond economical repair. That matters because an ordinary market-value settlement can be difficult to pin down for an older, rare, restored or unusually specified car. Agreed … Read more